
Which have home values greater than ever before, many are looking to money do it yourself projects and other expenditures utilising the equity in their home. Let us establish a few terms and conditions then examine the 2 very well-known house security created money: HELOC compared to Home Guarantee Loan.
What is https://cashadvanceamerica.net/20000-dollar-payday-loan/ Household Security?
As we possess a whole blog post answering that it matter (click “What is actually Domestic Guarantee” more than for more information) the latest quick version so is this:
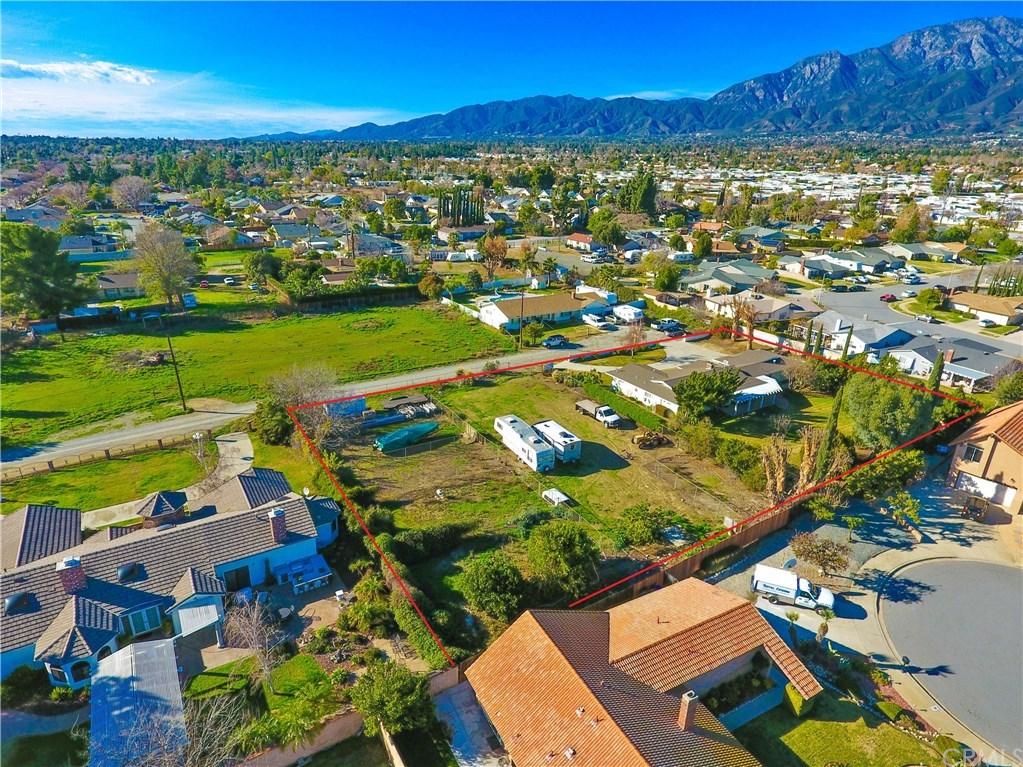
Family security is calculated as the really worth that might be came back to you in the event the family was marketed and all of your property-relevant costs have been reduced. Such, if for example the household sold getting $five-hundred,000 and also you due $three hundred,000 inside the money to the possessions, the significance returned to would certainly be $two hundred,000. Because of it analogy, your home collateral might be $2 hundred,000.
Nevertheless key to skills household collateral cost loans and you will domestic equity contours is the fact that the it’s not necessary to sell the house for taking benefit of new equity you’ve got into the it.
very first and you may 2nd Mortgage loans Outlined
An initial financial retains the first lien reputation to your assets (during the much easier words, it is first in line to locate paid down.)
The second mortgage keeps 2nd lien condition into the assets (or perhaps is the next loan discover paid, following the 1st.)
So you’re able to a resident, these types of significance usually do not matter a whole lot. But fundamentally, the fresh HELOC and you may Home Equity Mortgage selection we shall speak about here are both named next mortgage loans, which is useful to note.
When you find yourself someone who has already paid down your own home’s very first financial, your HELOC otherwise Family Equity financing do upcoming get into first lien reputation, instead of next. ?? Complicated, we realize.
House Equity Line of credit (HELOC)
A property equity personal line of credit (HELOC) is actually a line of credit which allows you to definitely make use of your own house’s collateral.
A little Instance a credit card
For example a charge card, a HELOC try a rotating personal line of credit which enables you so you can borrow to a specific restrict, pay it off, then borrow they again. You to definitely restriction is dependent upon a percentage that financial kits to you called the LTV (loan-to-value).
The fresh new LTV ‘s the proportion from simply how much your debt for the your home as opposed to how much it’s actually value. Don’t get worried throughout the figuring LTV oneself – instead, get in touch with our financing professionals to supply a customized address. Copper State Credit Union’s LTV restrict to have HELOCs are 80% – we would not create you to definitely use more than 80% of your house’s worthy of which have a house security range.
Time Limits? Strange.
Having a HELOC, earliest there was a draw several months. This can be basically a great ten-12 months period where you are able to withdraw and use the bucks when you look at the a good HELOC. You’ll be able to have a tendency to still have to make costs during this phase and you will those people payments will go on paying interest and people heading to reducing your principal balance. You can even mark a full level of new HELOC and you can repay it multiple times within this 10 years.
Next upwards is the cost several months. After you get to the payment windows, you’ll be able to no more have the ability to borrow funds. It is possible to initiate paying down the principal plus notice you’ve compiled. Repayment period basically persists ten years also.
Do We Meet the requirements?
In order to qualify for a beneficial HELOC, you will have to prove to the possible household equity lender you to it is possible to invest right back hardly any money your obtain. Their bank usually think about your obligations so you can income ratio (DTI), your credit rating, and worth of your house. The home guarantee lender that you choose for the HELOC really does not need to end up being the identical to your home loan provider.